View on GitHub
Open this notebook in GitHub to run it yourself
Dealing with Constraint Using Portfolio Optimization
Guidance for the Workshop:
The# TODO or # Your code is there for you to do yourself.
**The # Solution start and # Solution end are only for helping you.
Please delete the Solution and try doing it yourself…**
Portfolio Optimization with the Quantum Approximate Optimization Algorithm (QAOA)
Introduction
Portfolio optimization is the process of allocating a portfolio of financial assets optimally, according to some predetermined goal. Usually, the goal is to maximize the potential return while minimizing the financial risk of the portfolio. One can express this problem as a combinatorial optimization problem like many other real-world problems. In this demo, we’ll show how the Quantum Approximate Optimization Algorithm (QAOA) can be employed on the Classiq platform to solve the problem of portfolio optimization.Modeling the Portfolio Optimization Problem
As a first step, we have to model the problem mathematically. We will use a simple yet powerful model, which captures the essence of portfolio optimization:- A portfolio is built from a pool of n financial assets, each asset labeled i∈{1,…,n}.
- Every asset’s return is a random variable, with expected value μi and variance Σi (modeling the financial risk involved in the asset).
- Every two assets i=j have covariance Σij (modeling market correlation between assets).
- Every asset i has a weight wi∈Di={0,…,bi} in the portfolio, with bi defined as the budget for asset i (modeling the maximum allowed weight of the asset).
- The return vector μ, the covariance matrix Σ and the weight vector w are defined naturally from the above (with the domain D=D1×D2×…×Dn for w).
import math
from typing import List

import matplotlib.pyplot as plt
import networkx as nx
import numpy as np
from scipy.optimize import minimize

from classiq import *
Finaly, We Will Add Inequality Constraints:
w∈DminwTΣw−μTw, subject to: Σiwi≤B We will do it similarly to the equality constraint but we add slack variable that can take multiple values to make sure Σiwi≤B In this case, we will change the objective function as follows: w∈DminwTΣw−μTw+P∗(Σiwi+slack−B)2 Where P is the penalty value you need to define.The Portfolio Optimization Problem Parameters
First we define the parameters of the optimization problem, which include the expected return vector, the covariance matrix, the total budget and the asset-specific budgets.returns = np.array([3, 4, -1])
# fmt: off
covariances = np.array(
[
[ 0.9, 0.5, -0.7],
[ 0.5, 0.9, -0.2],
[-0.7, -0.2, 0.9],
]
)
# fmt: on
total_budget = 6
Defining the Variables
The number of slack qubits needs to reach to get to the number B.num_assets = 3
num_qubits_per_asset = 2 # Defines the possible values of choosing each asset.
num_slack = 3
class PortfolioOptimizationVars(QStruct):
a: QArray[QNum[num_qubits_per_asset], num_assets]
slack: QNum[num_slack]
Define the Expected Return
Define a function that describes μTw where μ is thereturn vector.
def expected_return_cost(
returns: np.ndarray, w_array: PortfolioOptimizationVars
) -> float:
return sum(returns[i] * w_array.a[i] for i in range(len(returns)))
Define the Risk Term
Define a function that describes the risk term in the objective function wTΣw where Σ is thecovariances matrix.
w∈DminwTΣw−μTw+P∗(Σiwi+slack−B)2
def risk_cost(covariances: np.ndarray, w_array: PortfolioOptimizationVars) -> float:
risk_term = sum(
w_array.a[i]
* sum(w_array.a[j] * covariances[i][j] for j in range(covariances.shape[0]))
for i in range(covariances.shape[0])
)
return risk_term
Define the Entire Portfolio Optimization Objective Function
Combine the risk term and the expected return functions. There a a term called return coefficientreturn_coeff that defines how much you prefer certainly over return.
Higher values is more risky but can be more profitable.
Later try changing it to see how the result changes.
return_coeff = 1.4
Penalty = 1.3
def objective_portfolio_inequality(
w_array: PortfolioOptimizationVars,
returns: np.ndarray,
covariances: np.ndarray,
return_coeff: float,
) -> float:
# Your code
# Solution start
return (
risk_cost(covariances, w_array)
- return_coeff * expected_return_cost(returns, w_array)
+ Penalty
* (
sum(w_array.a[i] for i in range(len(returns)))
+ w_array.slack
- total_budget
)
** 2
)
# Solution end
Build the QAOA Circuit
@qfunc
def mixer_layer(beta: CReal, qba: QArray):
# Your code here
# Solution start
apply_to_all(lambda q: RX(beta, q), qba)
# Solution end
NUM_LAYERS = 4
@qfunc
def main(
params: CArray[CReal, 2 * NUM_LAYERS], w_array: Output[PortfolioOptimizationVars]
) -> None:
# Allocating the qubits
allocate(w_array)
# Your code
# Solution start
hadamard_transform(w_array)
repeat(
count=int(params.len / 2),
iteration=lambda i: (
phase(
objective_portfolio_inequality(
w_array, returns, covariances, return_coeff
),
params[2 * i],
),
mixer_layer(params[2 * i + 1], w_array),
),
)
# Solution end
Synthesizing and Visualizing
qprog = synthesize(main)
show(qprog)
Output:
Quantum program link: https://platform.classiq.io/circuit/3Ioao5hQ1Ht6QPbjxMSyc83kmXD
Output:
https://platform.classiq.io/circuit/3Ioao5hQ1Ht6QPbjxMSyc83kmXD?login=True&version=22
Execution and Post Processing
For the hybrid execution, we useExecutionSession, which can evaluate the circuit in multiple methods, such as sampling the circuit, giving specific values for the parameters, and evaluating to a specific Hamiltonian, which is very common in chemical applications.
In QAOA, we will use the estimate_cost method, which samples the cost function and returns their average cost from all measurements.
That helps to optimize easily.
NUM_SHOTS = 1000
es = ExecutionSession(qprog, num_shots=NUM_SHOTS)
# Build `initial_params` list of np.array type.
# The gamma values should start from 0 and, in each layer, should approach closer to 1 linearly
# The beta values should start from 1 and in each layer, should approach closer to 0 linearly
# Then unify it to one list so scipy minimize can digest it.
# Your code here
# Solution start
def initial_qaoa_params(NUM_LAYERS) -> np.ndarray:
initial_gammas = math.pi * np.linspace(0, 1, NUM_LAYERS)
initial_betas = math.pi * np.linspace(1, 0, NUM_LAYERS)
initial_params = []
for i in range(NUM_LAYERS):
initial_params.append(initial_gammas[i])
initial_params.append(initial_betas[i])
return np.array(initial_params)
# Solution end
initial_params = initial_qaoa_params(NUM_LAYERS)
Define a Callback Function to Track the Optimization
# Record the steps of the optimization
intermediate_params = []
objective_values = []
# Define the callback function to store the intermediate steps
def callback(xk):
intermediate_params.append(xk)
Define the Objective Function
# You code
# You can use the hints in the comments
# cost_func = lambda state: objective_portfolio_inequality(
# w_array = ...,
# returns = ...,
# covariances = ...,
# return_coeff= ...
# )
# def estimate_cost_func(params: np.ndarray) -> float:
# objective_value = es.estimate_cost(
# cost_func = ...,
# parameters = {"params": params.tolist()}
# )
# # Your code here
# # Save the result for convergence graph
# return objective_value
# Solution start
cost_func = lambda state: objective_portfolio_inequality(
w_array=state["w_array"],
returns=returns,
covariances=covariances,
return_coeff=return_coeff,
)
def estimate_cost_func(params: np.ndarray) -> float:
objective_value = es.estimate_cost(
cost_func=cost_func, parameters={"params": params.tolist()}
)
objective_values.append(objective_value)
return objective_value
# Solution end
Optimize
# You code
# You can use the hints in the comments
# optimization_res = minimize(
# fun = ...,
# x0=...,
# method="COBYLA",
# callback=...,
# options={"maxiter": 10},
# )
# Solution start
optimization_res = minimize(
estimate_cost_func,
x0=initial_params,
method="COBYLA",
callback=callback,
options={"maxiter": 20},
)
# Solution end
Look at the Results
res = es.sample({"params": optimization_res.x.tolist()})
print(f"Optimized parameters: {optimization_res.x.tolist()}")
sorted_counts = sorted(
res.parsed_counts,
key=lambda pc: objective_portfolio_inequality(
pc.state["w_array"],
returns=returns,
covariances=covariances,
return_coeff=return_coeff,
),
)
for sampled in sorted_counts:
w_sample = sampled.state["w_array"]
print(
f"solution={w_sample} probability={sampled.shots/NUM_SHOTS} "
f"cost={objective_portfolio_inequality(w_array=w_sample,returns = returns, covariances = covariances, return_coeff= return_coeff)}"
)
Output:
Optimized parameters: [-0.0819498722414829, 2.504375766610053, 0.5485136457459014, 3.6632130644867122, 1.4352072591698994, 1.011183391518206, 2.94603162121815, 0.033065870111043345]
solution={'a': [2, 2, 1], 'slack': 1} probability=0.004 cost=-9.700000000000001
solution={'a': [2, 3, 1], 'slack': 0} probability=0.002 cost=-9.199999999999998
solution={'a': [3, 1, 2], 'slack': 0} probability=0.004 cost=-8.999999999999998
solution={'a': [1, 2, 0], 'slack': 3} probability=0.001 cost=-8.899999999999999
solution={'a': [1, 2, 1], 'slack': 2} probability=0.001 cost=-8.8
solution={'a': [3, 2, 1], 'slack': 0} probability=0.005 cost=-8.799999999999999
solution={'a': [0, 3, 0], 'slack': 3} probability=0.005 cost=-8.699999999999996
solution={'a': [2, 1, 1], 'slack': 2} probability=0.01 cost=-8.4
solution={'a': [2, 2, 1], 'slack': 2} probability=0.004 cost=-8.4
solution={'a': [2, 2, 1], 'slack': 0} probability=0.002 cost=-8.4
solution={'a': [3, 2, 2], 'slack': 0} probability=0.002 cost=-8.399999999999999
solution={'a': [2, 2, 0], 'slack': 2} probability=0.001 cost=-8.399999999999999
solution={'a': [1, 3, 1], 'slack': 2} probability=0.001 cost=-7.999999999999999
solution={'a': [2, 2, 2], 'slack': 1} probability=0.006 cost=-7.899999999999998
solution={'a': [2, 3, 1], 'slack': 1} probability=0.001 cost=-7.899999999999998
solution={'a': [2, 3, 2], 'slack': 0} probability=0.007 cost=-7.8
solution={'a': [1, 3, 2], 'slack': 0} probability=0.002 cost=-7.799999999999999
solution={'a': [3, 1, 2], 'slack': 1} probability=0.005 cost=-7.699999999999998
solution={'a': [1, 3, 0], 'slack': 1} probability=0.001 cost=-7.699999999999998
solution={'a': [0, 2, 0], 'slack': 4} probability=0.009 cost=-7.6
solution={'a': [0, 3, 1], 'slack': 2} probability=0.002 cost=-7.599999999999999
solution={'a': [1, 2, 0], 'slack': 4} probability=0.001 cost=-7.599999999999999
solution={'a': [1, 2, 1], 'slack': 3} probability=0.003 cost=-7.500000000000001
solution={'a': [2, 1, 0], 'slack': 3} probability=0.002 cost=-7.5
solution={'a': [2, 1, 2], 'slack': 1} probability=0.008 cost=-7.499999999999999
solution={'a': [3, 2, 1], 'slack': 1} probability=0.005 cost=-7.499999999999999
solution={'a': [2, 3, 0], 'slack': 1} probability=0.003 cost=-7.4999999999999964
solution={'a': [0, 3, 0], 'slack': 2} probability=0.001 cost=-7.399999999999996
solution={'a': [3, 1, 1], 'slack': 2} probability=0.002 cost=-7.199999999999998
solution={'a': [2, 2, 0], 'slack': 3} probability=0.006 cost=-7.099999999999999
solution={'a': [2, 2, 0], 'slack': 1} probability=0.002 cost=-7.099999999999999
solution={'a': [1, 2, 2], 'slack': 1} probability=0.004 cost=-6.9
solution={'a': [1, 3, 2], 'slack': 1} probability=0.008 cost=-6.499999999999999
solution={'a': [1, 1, 1], 'slack': 3} probability=0.002 cost=-6.499999999999998
solution={'a': [3, 0, 1], 'slack': 2} probability=0.004 cost=-6.399999999999999
solution={'a': [0, 2, 0], 'slack': 3} probability=0.004 cost=-6.3
solution={'a': [0, 2, 0], 'slack': 5} probability=0.001 cost=-6.3
solution={'a': [0, 3, 1], 'slack': 1} probability=0.009 cost=-6.299999999999999
solution={'a': [0, 3, 1], 'slack': 3} probability=0.003 cost=-6.299999999999999
solution={'a': [2, 1, 0], 'slack': 4} probability=0.003 cost=-6.2
solution={'a': [2, 1, 0], 'slack': 2} probability=0.001 cost=-6.2
solution={'a': [2, 1, 2], 'slack': 2} probability=0.003 cost=-6.199999999999999
solution={'a': [2, 1, 2], 'slack': 0} probability=0.002 cost=-6.199999999999999
solution={'a': [3, 1, 0], 'slack': 2} probability=0.004 cost=-6.1999999999999975
solution={'a': [2, 3, 0], 'slack': 0} probability=0.006 cost=-6.199999999999997
solution={'a': [2, 3, 0], 'slack': 2} probability=0.004 cost=-6.199999999999997
solution={'a': [0, 2, 1], 'slack': 3} probability=0.001 cost=-6.099999999999999
solution={'a': [3, 2, 0], 'slack': 1} probability=0.003 cost=-6.099999999999994
solution={'a': [3, 3, 1], 'slack': 0} probability=0.003 cost=-6.000000000000001
solution={'a': [1, 1, 0], 'slack': 3} probability=0.005 cost=-5.699999999999999
solution={'a': [1, 2, 2], 'slack': 2} probability=0.002 cost=-5.6000000000000005
solution={'a': [1, 2, 2], 'slack': 0} probability=0.001 cost=-5.6000000000000005
solution={'a': [2, 2, 3], 'slack': 0} probability=0.001 cost=-5.599999999999999
solution={'a': [2, 0, 1], 'slack': 3} probability=0.002 cost=-5.3
solution={'a': [1, 1, 1], 'slack': 4} probability=0.003 cost=-5.199999999999998
solution={'a': [3, 0, 2], 'slack': 2} probability=0.003 cost=-5.1999999999999975
solution={'a': [3, 0, 1], 'slack': 1} probability=0.004 cost=-5.099999999999999
solution={'a': [3, 0, 1], 'slack': 3} probability=0.003 cost=-5.099999999999999
solution={'a': [0, 2, 1], 'slack': 2} probability=0.002 cost=-4.799999999999999
solution={'a': [2, 0, 0], 'slack': 4} probability=0.001 cost=-4.799999999999999
solution={'a': [0, 2, 1], 'slack': 4} probability=0.001 cost=-4.799999999999999
solution={'a': [3, 0, 3], 'slack': 0} probability=0.008 cost=-4.799999999999995
solution={'a': [3, 2, 0], 'slack': 2} probability=0.009 cost=-4.7999999999999945
solution={'a': [0, 1, 0], 'slack': 5} probability=0.002 cost=-4.699999999999999
solution={'a': [3, 2, 2], 'slack': 1} probability=0.003 cost=-4.499999999999999
solution={'a': [3, 0, 0], 'slack': 3} probability=0.001 cost=-4.499999999999998
solution={'a': [1, 1, 2], 'slack': 2} probability=0.004 cost=-4.199999999999999
solution={'a': [1, 3, 1], 'slack': 3} probability=0.003 cost=-4.099999999999999
solution={'a': [2, 0, 1], 'slack': 4} probability=0.004 cost=-4.0
solution={'a': [2, 0, 1], 'slack': 2} probability=0.002 cost=-4.0
solution={'a': [2, 3, 1], 'slack': 2} probability=0.006 cost=-3.9999999999999973
solution={'a': [2, 3, 2], 'slack': 1} probability=0.005 cost=-3.8999999999999995
solution={'a': [1, 3, 0], 'slack': 4} probability=0.003 cost=-3.799999999999998
solution={'a': [1, 3, 0], 'slack': 0} probability=0.002 cost=-3.799999999999998
solution={'a': [1, 2, 0], 'slack': 1} probability=0.003 cost=-3.6999999999999984
solution={'a': [3, 2, 1], 'slack': 2} probability=0.001 cost=-3.5999999999999988
solution={'a': [2, 0, 0], 'slack': 3} probability=0.011 cost=-3.499999999999999
solution={'a': [2, 0, 0], 'slack': 5} probability=0.002 cost=-3.499999999999999
solution={'a': [2, 1, 3], 'slack': 1} probability=0.003 cost=-3.4999999999999982
solution={'a': [3, 0, 3], 'slack': 1} probability=0.005 cost=-3.4999999999999956
solution={'a': [0, 3, 0], 'slack': 5} probability=0.004 cost=-3.4999999999999956
solution={'a': [0, 1, 0], 'slack': 4} probability=0.003 cost=-3.3999999999999995
solution={'a': [0, 3, 2], 'slack': 0} probability=0.002 cost=-3.3999999999999995
solution={'a': [3, 3, 2], 'slack': 0} probability=0.002 cost=-3.3999999999999977
solution={'a': [1, 0, 0], 'slack': 5} probability=0.003 cost=-3.2999999999999994
solution={'a': [3, 1, 1], 'slack': 3} probability=0.004 cost=-3.299999999999998
solution={'a': [2, 1, 1], 'slack': 4} probability=0.007 cost=-3.2
solution={'a': [2, 2, 0], 'slack': 4} probability=0.009 cost=-3.1999999999999984
solution={'a': [3, 0, 0], 'slack': 4} probability=0.003 cost=-3.1999999999999984
solution={'a': [3, 0, 0], 'slack': 2} probability=0.001 cost=-3.1999999999999984
solution={'a': [1, 3, 3], 'slack': 0} probability=0.005 cost=-3.1999999999999966
solution={'a': [1, 1, 2], 'slack': 1} probability=0.008 cost=-2.8999999999999995
solution={'a': [1, 1, 2], 'slack': 3} probability=0.007 cost=-2.8999999999999995
solution={'a': [3, 3, 0], 'slack': 1} probability=0.009 cost=-2.899999999999996
solution={'a': [0, 1, 1], 'slack': 4} probability=0.001 cost=-2.7999999999999994
solution={'a': [0, 2, 2], 'slack': 2} probability=0.001 cost=-2.799999999999999
solution={'a': [2, 0, 2], 'slack': 1} probability=0.002 cost=-2.6999999999999993
solution={'a': [2, 0, 2], 'slack': 3} probability=0.001 cost=-2.6999999999999993
solution={'a': [1, 3, 2], 'slack': 2} probability=0.005 cost=-2.5999999999999988
solution={'a': [3, 1, 3], 'slack': 1} probability=0.001 cost=-2.4999999999999973
solution={'a': [0, 2, 0], 'slack': 6} probability=0.006 cost=-2.3999999999999995
solution={'a': [1, 0, 1], 'slack': 4} probability=0.004 cost=-2.3999999999999995
solution={'a': [0, 2, 0], 'slack': 2} probability=0.003 cost=-2.3999999999999995
solution={'a': [0, 3, 1], 'slack': 0} probability=0.007 cost=-2.3999999999999986
solution={'a': [2, 1, 0], 'slack': 1} probability=0.005 cost=-2.3
solution={'a': [2, 3, 0], 'slack': 3} probability=0.001 cost=-2.2999999999999963
solution={'a': [3, 3, 1], 'slack': 1} probability=0.001 cost=-2.1000000000000005
solution={'a': [1, 0, 0], 'slack': 6} probability=0.007 cost=-1.9999999999999993
solution={'a': [1, 0, 0], 'slack': 4} probability=0.003 cost=-1.9999999999999993
solution={'a': [2, 3, 3], 'slack': 0} probability=0.003 cost=-1.9999999999999991
solution={'a': [1, 2, 3], 'slack': 1} probability=0.007 cost=-1.8999999999999992
solution={'a': [1, 1, 0], 'slack': 6} probability=0.007 cost=-1.799999999999999
solution={'a': [1, 1, 0], 'slack': 2} probability=0.001 cost=-1.799999999999999
solution={'a': [1, 2, 2], 'slack': 3} probability=0.003 cost=-1.7000000000000002
solution={'a': [0, 1, 1], 'slack': 3} probability=0.002 cost=-1.4999999999999993
solution={'a': [0, 2, 2], 'slack': 1} probability=0.007 cost=-1.499999999999999
solution={'a': [0, 2, 2], 'slack': 3} probability=0.001 cost=-1.499999999999999
solution={'a': [1, 1, 1], 'slack': 1} probability=0.005 cost=-1.299999999999998
solution={'a': [1, 1, 1], 'slack': 5} probability=0.002 cost=-1.299999999999998
solution={'a': [3, 0, 2], 'slack': 3} probability=0.001 cost=-1.2999999999999972
solution={'a': [3, 0, 1], 'slack': 0} probability=0.001 cost=-1.1999999999999984
solution={'a': [1, 0, 1], 'slack': 3} probability=0.006 cost=-1.0999999999999994
solution={'a': [0, 2, 1], 'slack': 1} probability=0.002 cost=-0.8999999999999986
solution={'a': [0, 2, 1], 'slack': 5} probability=0.001 cost=-0.8999999999999986
solution={'a': [3, 2, 0], 'slack': 3} probability=0.005 cost=-0.8999999999999941
solution={'a': [2, 0, 1], 'slack': 1} probability=0.006 cost=-0.09999999999999964
solution={'a': [1, 1, 3], 'slack': 1} probability=0.002 cost=-0.09999999999999964
solution={'a': [2, 0, 1], 'slack': 5} probability=0.001 cost=-0.09999999999999964
solution={'a': [0, 0, 0], 'slack': 6} probability=0.005 cost=0.0
solution={'a': [1, 0, 2], 'slack': 3} probability=0.001 cost=0.30000000000000027
solution={'a': [2, 0, 0], 'slack': 2} probability=0.01 cost=0.40000000000000124
solution={'a': [2, 0, 3], 'slack': 2} probability=0.001 cost=0.40000000000000235
solution={'a': [0, 3, 2], 'slack': 3} probability=0.004 cost=0.5000000000000009
solution={'a': [3, 0, 0], 'slack': 5} probability=0.002 cost=0.700000000000002
solution={'a': [1, 3, 3], 'slack': 1} probability=0.001 cost=0.7000000000000037
solution={'a': [1, 1, 2], 'slack': 4} probability=0.003 cost=1.0000000000000009
solution={'a': [1, 1, 2], 'slack': 0} probability=0.002 cost=1.0000000000000009
solution={'a': [1, 1, 3], 'slack': 0} probability=0.002 cost=1.2000000000000004
solution={'a': [2, 0, 2], 'slack': 4} probability=0.003 cost=1.200000000000001
solution={'a': [0, 0, 0], 'slack': 5} probability=0.001 cost=1.3
solution={'a': [0, 3, 3], 'slack': 1} probability=0.002 cost=1.3000000000000018
solution={'a': [1, 0, 2], 'slack': 4} probability=0.007 cost=1.6000000000000003
solution={'a': [1, 0, 2], 'slack': 2} probability=0.006 cost=1.6000000000000003
solution={'a': [1, 0, 0], 'slack': 3} probability=0.001 cost=1.9000000000000008
solution={'a': [2, 2, 1], 'slack': 4} probability=0.001 cost=2.0
solution={'a': [1, 2, 3], 'slack': 2} probability=0.006 cost=2.000000000000001
solution={'a': [0, 1, 1], 'slack': 2} probability=0.002 cost=2.400000000000001
solution={'a': [0, 1, 1], 'slack': 6} probability=0.001 cost=2.400000000000001
solution={'a': [0, 2, 2], 'slack': 4} probability=0.011 cost=2.4000000000000012
solution={'a': [1, 3, 1], 'slack': 4} probability=0.006 cost=2.400000000000002
solution={'a': [2, 3, 1], 'slack': 3} probability=0.002 cost=2.5000000000000036
solution={'a': [2, 3, 2], 'slack': 2} probability=0.005 cost=2.6000000000000014
solution={'a': [1, 0, 1], 'slack': 2} probability=0.007 cost=2.8000000000000007
solution={'a': [1, 0, 1], 'slack': 6} probability=0.007 cost=2.8000000000000007
solution={'a': [1, 2, 0], 'slack': 6} probability=0.003 cost=2.8000000000000025
solution={'a': [1, 2, 0], 'slack': 0} probability=0.001 cost=2.8000000000000025
solution={'a': [3, 2, 1], 'slack': 3} probability=0.002 cost=2.900000000000002
solution={'a': [0, 3, 0], 'slack': 0} probability=0.001 cost=3.0000000000000053
solution={'a': [3, 3, 2], 'slack': 1} probability=0.003 cost=3.100000000000003
solution={'a': [3, 1, 1], 'slack': 4} probability=0.006 cost=3.200000000000003
solution={'a': [0, 0, 1], 'slack': 6} probability=0.02 cost=3.5999999999999996
solution={'a': [0, 0, 1], 'slack': 4} probability=0.001 cost=3.5999999999999996
solution={'a': [0, 2, 3], 'slack': 0} probability=0.004 cost=3.6000000000000005
solution={'a': [0, 2, 3], 'slack': 2} probability=0.001 cost=3.6000000000000005
solution={'a': [3, 1, 3], 'slack': 2} probability=0.002 cost=4.0000000000000036
solution={'a': [0, 2, 0], 'slack': 1} probability=0.006 cost=4.100000000000001
solution={'a': [0, 2, 0], 'slack': 7} probability=0.003 cost=4.100000000000001
solution={'a': [0, 3, 1], 'slack': 5} probability=0.001 cost=4.100000000000002
solution={'a': [2, 1, 0], 'slack': 0} probability=0.003 cost=4.200000000000001
solution={'a': [2, 1, 2], 'slack': 4} probability=0.003 cost=4.200000000000002
solution={'a': [2, 3, 0], 'slack': 4} probability=0.003 cost=4.200000000000005
solution={'a': [2, 3, 3], 'slack': 1} probability=0.002 cost=4.500000000000002
solution={'a': [1, 1, 0], 'slack': 1} probability=0.009 cost=4.700000000000002
solution={'a': [1, 0, 3], 'slack': 2} probability=0.002 cost=4.800000000000001
solution={'a': [2, 2, 3], 'slack': 2} probability=0.002 cost=4.8000000000000025
solution={'a': [1, 1, 3], 'slack': 3} probability=0.001 cost=5.1000000000000005
solution={'a': [0, 0, 0], 'slack': 4} probability=0.004 cost=5.2
solution={'a': [0, 3, 3], 'slack': 2} probability=0.005 cost=5.200000000000002
solution={'a': [1, 1, 1], 'slack': 6} probability=0.003 cost=5.200000000000003
solution={'a': [3, 0, 2], 'slack': 4} probability=0.004 cost=5.200000000000004
solution={'a': [3, 0, 1], 'slack': 5} probability=0.006 cost=5.3000000000000025
solution={'a': [1, 0, 2], 'slack': 1} probability=0.007 cost=5.5
solution={'a': [0, 2, 1], 'slack': 6} probability=0.002 cost=5.600000000000002
solution={'a': [3, 2, 0], 'slack': 4} probability=0.004 cost=5.600000000000007
solution={'a': [1, 0, 3], 'slack': 3} probability=0.003 cost=6.1000000000000005
solution={'a': [0, 1, 2], 'slack': 5} probability=0.001 cost=6.1000000000000005
solution={'a': [0, 1, 2], 'slack': 1} probability=0.001 cost=6.1000000000000005
solution={'a': [2, 0, 1], 'slack': 0} probability=0.003 cost=6.400000000000001
solution={'a': [2, 0, 0], 'slack': 1} probability=0.004 cost=6.900000000000002
solution={'a': [2, 0, 0], 'slack': 7} probability=0.002 cost=6.900000000000002
solution={'a': [3, 0, 3], 'slack': 3} probability=0.003 cost=6.900000000000006
solution={'a': [0, 1, 0], 'slack': 2} probability=0.003 cost=7.000000000000002
solution={'a': [3, 0, 0], 'slack': 6} probability=0.002 cost=7.200000000000003
solution={'a': [1, 3, 3], 'slack': 2} probability=0.001 cost=7.200000000000005
solution={'a': [0, 0, 1], 'slack': 7} probability=0.005 cost=7.5
solution={'a': [0, 0, 1], 'slack': 3} probability=0.001 cost=7.5
solution={'a': [0, 2, 3], 'slack': 3} probability=0.001 cost=7.500000000000001
solution={'a': [1, 1, 2], 'slack': 5} probability=0.001 cost=7.500000000000002
solution={'a': [0, 0, 2], 'slack': 3} probability=0.012 cost=7.7
solution={'a': [0, 1, 3], 'slack': 3} probability=0.003 cost=7.7
solution={'a': [0, 1, 3], 'slack': 1} probability=0.001 cost=7.7
solution={'a': [1, 0, 0], 'slack': 2} probability=0.001 cost=8.400000000000002
solution={'a': [1, 2, 3], 'slack': 3} probability=0.006 cost=8.500000000000002
solution={'a': [0, 2, 2], 'slack': 5} probability=0.003 cost=8.900000000000002
solution={'a': [0, 1, 1], 'slack': 7} probability=0.002 cost=8.900000000000002
solution={'a': [1, 0, 1], 'slack': 1} probability=0.004 cost=9.3
solution={'a': [1, 0, 1], 'slack': 7} probability=0.003 cost=9.3
solution={'a': [1, 0, 3], 'slack': 4} probability=0.004 cost=10.0
solution={'a': [3, 2, 2], 'slack': 3} probability=0.003 cost=11.100000000000001
solution={'a': [0, 1, 3], 'slack': 4} probability=0.011 cost=11.600000000000001
solution={'a': [1, 1, 3], 'slack': 4} probability=0.004 cost=11.600000000000001
solution={'a': [0, 1, 3], 'slack': 0} probability=0.003 cost=11.600000000000001
solution={'a': [0, 0, 2], 'slack': 2} probability=0.001 cost=11.600000000000001
solution={'a': [2, 3, 1], 'slack': 4} probability=0.007 cost=11.600000000000003
solution={'a': [2, 2, 2], 'slack': 4} probability=0.001 cost=11.600000000000003
solution={'a': [0, 0, 0], 'slack': 3} probability=0.004 cost=11.700000000000001
solution={'a': [2, 3, 2], 'slack': 3} probability=0.004 cost=11.700000000000001
solution={'a': [0, 3, 3], 'slack': 3} probability=0.003 cost=11.700000000000003
solution={'a': [1, 3, 0], 'slack': 6} probability=0.001 cost=11.800000000000002
solution={'a': [1, 2, 0], 'slack': 7} probability=0.001 cost=11.900000000000002
solution={'a': [1, 2, 1], 'slack': 6} probability=0.001 cost=12.0
solution={'a': [1, 0, 2], 'slack': 0} probability=0.002 cost=12.000000000000002
solution={'a': [3, 2, 1], 'slack': 4} probability=0.001 cost=12.000000000000002
solution={'a': [1, 0, 2], 'slack': 6} probability=0.001 cost=12.000000000000002
solution={'a': [0, 3, 0], 'slack': 7} probability=0.001 cost=12.100000000000005
solution={'a': [3, 3, 2], 'slack': 2} probability=0.003 cost=12.200000000000003
solution={'a': [0, 0, 3], 'slack': 3} probability=0.003 cost=12.3
solution={'a': [2, 1, 1], 'slack': 6} probability=0.007 cost=12.4
solution={'a': [2, 2, 0], 'slack': 6} probability=0.001 cost=12.400000000000002
solution={'a': [0, 1, 2], 'slack': 0} probability=0.002 cost=12.600000000000001
solution={'a': [3, 3, 3], 'slack': 1} probability=0.001 cost=12.700000000000003
solution={'a': [3, 1, 3], 'slack': 3} probability=0.006 cost=13.100000000000003
solution={'a': [0, 2, 0], 'slack': 0} probability=0.003 cost=13.200000000000001
solution={'a': [0, 3, 1], 'slack': 6} probability=0.001 cost=13.200000000000003
solution={'a': [2, 1, 0], 'slack': 7} probability=0.003 cost=13.3
solution={'a': [2, 3, 0], 'slack': 5} probability=0.002 cost=13.300000000000004
solution={'a': [3, 3, 1], 'slack': 3} probability=0.002 cost=13.5
solution={'a': [0, 0, 3], 'slack': 4} probability=0.003 cost=13.600000000000001
solution={'a': [0, 0, 3], 'slack': 2} probability=0.001 cost=13.600000000000001
solution={'a': [2, 3, 3], 'slack': 2} probability=0.001 cost=13.600000000000001
solution={'a': [1, 1, 0], 'slack': 0} probability=0.006 cost=13.8
solution={'a': [2, 2, 3], 'slack': 3} probability=0.001 cost=13.900000000000002
solution={'a': [0, 0, 1], 'slack': 2} probability=0.002 cost=14.0
solution={'a': [0, 2, 3], 'slack': 4} probability=0.003 cost=14.000000000000002
solution={'a': [3, 0, 1], 'slack': 6} probability=0.001 cost=14.400000000000002
solution={'a': [3, 1, 0], 'slack': 6} probability=0.001 cost=14.600000000000003
solution={'a': [0, 2, 1], 'slack': 7} probability=0.001 cost=14.700000000000003
solution={'a': [3, 2, 0], 'slack': 5} probability=0.001 cost=14.700000000000006
solution={'a': [2, 0, 0], 'slack': 0} probability=0.002 cost=16.0
solution={'a': [3, 0, 3], 'slack': 4} probability=0.002 cost=16.000000000000007
solution={'a': [0, 1, 0], 'slack': 1} probability=0.003 cost=16.1
solution={'a': [1, 3, 3], 'slack': 3} probability=0.005 cost=16.300000000000004
solution={'a': [1, 0, 3], 'slack': 5} probability=0.001 cost=16.5
solution={'a': [2, 0, 2], 'slack': 6} probability=0.001 cost=16.8
solution={'a': [1, 0, 0], 'slack': 1} probability=0.006 cost=17.5
solution={'a': [0, 0, 3], 'slack': 1} probability=0.002 cost=17.5
solution={'a': [0, 0, 2], 'slack': 7} probability=0.006 cost=18.1
solution={'a': [0, 1, 3], 'slack': 5} probability=0.001 cost=18.1
solution={'a': [0, 0, 2], 'slack': 1} probability=0.001 cost=18.1
solution={'a': [1, 0, 1], 'slack': 0} probability=0.003 cost=18.400000000000002
solution={'a': [1, 1, 3], 'slack': 5} probability=0.002 cost=20.700000000000003
solution={'a': [0, 0, 0], 'slack': 2} probability=0.001 cost=20.8
solution={'a': [0, 3, 3], 'slack': 4} probability=0.001 cost=20.800000000000004
solution={'a': [0, 1, 2], 'slack': 7} probability=0.001 cost=21.700000000000003
solution={'a': [3, 2, 2], 'slack': 4} probability=0.004 cost=22.8
solution={'a': [0, 0, 1], 'slack': 1} probability=0.005 cost=23.1
solution={'a': [2, 3, 2], 'slack': 4} probability=0.001 cost=23.4
solution={'a': [3, 1, 2], 'slack': 5} probability=0.003 cost=23.5
solution={'a': [3, 2, 3], 'slack': 3} probability=0.001 cost=23.700000000000003
solution={'a': [3, 3, 2], 'slack': 3} probability=0.002 cost=23.900000000000002
solution={'a': [0, 0, 3], 'slack': 6} probability=0.002 cost=24.0
solution={'a': [0, 0, 3], 'slack': 0} probability=0.001 cost=24.0
solution={'a': [3, 3, 3], 'slack': 2} probability=0.001 cost=24.400000000000002
solution={'a': [3, 1, 3], 'slack': 4} probability=0.002 cost=24.800000000000004
solution={'a': [2, 3, 0], 'slack': 6} probability=0.001 cost=25.000000000000004
solution={'a': [2, 3, 3], 'slack': 3} probability=0.001 cost=25.3
solution={'a': [1, 0, 3], 'slack': 6} probability=0.001 cost=25.6
solution={'a': [3, 0, 2], 'slack': 6} probability=0.001 cost=26.000000000000004
solution={'a': [3, 0, 1], 'slack': 7} probability=0.002 cost=26.1
solution={'a': [3, 2, 0], 'slack': 6} probability=0.001 cost=26.400000000000006
solution={'a': [0, 0, 2], 'slack': 0} probability=0.002 cost=27.200000000000003
solution={'a': [0, 3, 2], 'slack': 6} probability=0.002 cost=27.8
solution={'a': [1, 1, 2], 'slack': 7} probability=0.001 cost=28.3
solution={'a': [3, 3, 0], 'slack': 5} probability=0.003 cost=28.300000000000004
solution={'a': [1, 0, 0], 'slack': 0} probability=0.003 cost=29.2
solution={'a': [0, 2, 2], 'slack': 7} probability=0.003 cost=29.700000000000003
solution={'a': [1, 1, 3], 'slack': 6} probability=0.001 cost=32.4
solution={'a': [0, 0, 0], 'slack': 1} probability=0.001 cost=32.5
solution={'a': [0, 0, 3], 'slack': 7} probability=0.001 cost=33.1
solution={'a': [0, 0, 1], 'slack': 0} probability=0.009 cost=34.8
solution={'a': [0, 2, 3], 'slack': 6} probability=0.003 cost=34.8
solution={'a': [3, 2, 2], 'slack': 5} probability=0.001 cost=37.10000000000001
solution={'a': [3, 1, 2], 'slack': 6} probability=0.001 cost=37.800000000000004
solution={'a': [3, 3, 2], 'slack': 4} probability=0.009 cost=38.2
solution={'a': [3, 3, 3], 'slack': 3} probability=0.001 cost=38.7
solution={'a': [0, 1, 3], 'slack': 7} probability=0.005 cost=38.9
solution={'a': [1, 3, 2], 'slack': 6} probability=0.006 cost=39.00000000000001
solution={'a': [3, 1, 3], 'slack': 5} probability=0.002 cost=39.10000000000001
solution={'a': [2, 3, 3], 'slack': 4} probability=0.001 cost=39.60000000000001
solution={'a': [3, 0, 2], 'slack': 7} probability=0.001 cost=40.300000000000004
solution={'a': [3, 2, 0], 'slack': 7} probability=0.002 cost=40.70000000000001
solution={'a': [2, 1, 3], 'slack': 6} probability=0.005 cost=42.00000000000001
solution={'a': [3, 0, 3], 'slack': 6} probability=0.001 cost=42.00000000000001
solution={'a': [0, 3, 3], 'slack': 6} probability=0.001 cost=46.800000000000004
solution={'a': [0, 2, 3], 'slack': 7} probability=0.002 cost=49.10000000000001
solution={'a': [2, 2, 2], 'slack': 7} probability=0.002 cost=54.50000000000001
solution={'a': [3, 2, 1], 'slack': 7} probability=0.001 cost=54.900000000000006
solution={'a': [3, 3, 3], 'slack': 4} probability=0.001 cost=55.60000000000001
solution={'a': [3, 3, 1], 'slack': 6} probability=0.001 cost=56.400000000000006
solution={'a': [2, 2, 3], 'slack': 6} probability=0.007 cost=56.800000000000004
solution={'a': [3, 0, 3], 'slack': 7} probability=0.001 cost=58.900000000000006
solution={'a': [0, 3, 3], 'slack': 7} probability=0.001 cost=63.7
solution={'a': [3, 3, 2], 'slack': 6} probability=0.004 cost=74.60000000000001
solution={'a': [3, 3, 3], 'slack': 5} probability=0.001 cost=75.10000000000001
solution={'a': [1, 3, 3], 'slack': 7} probability=0.001 cost=78.7
solution={'a': [3, 2, 3], 'slack': 7} probability=0.002 cost=96.5
solution={'a': [3, 3, 3], 'slack': 7} probability=0.001 cost=121.9
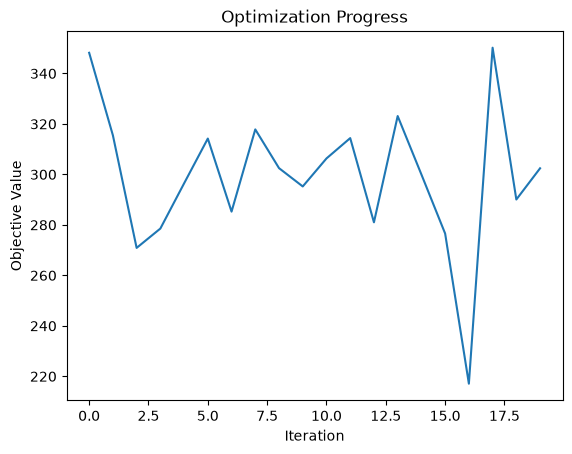
Convergence Graph
plt.plot(objective_values)
plt.xlabel("Iteration")
plt.ylabel("Objective Value")
plt.title("Optimization Progress")
Output:
Text(0.5, 1.0, 'Optimization Progress')
Solution
import math
from typing import List
import matplotlib.pyplot as plt
import networkx as nx
import numpy as np
from scipy.optimize import minimize
from classiq import *
NUM_LAYERS = 3
num_slack = 3
returns = np.array([3, 4, -1])
# fmt: off
covariances = np.array(
    [
        [ 0.9,  0.5, -0.7],
        [ 0.5,  0.9, -0.2],
        [-0.7, -0.2,  0.9],
    ]
)
# fmt: on
total_budget = 6
specific_budgets = 3
return_coeff = 10.0
num_assets = 3
num_qubits_per_asset = 2
Penalty = 30.5
# start with integer variables
class PortfolioOptimizationVars(QStruct):
a: QArray[QNum[num_qubits_per_asset], num_assets]
slack: QNum[num_slack]
def expected_return_cost(
    returns: np.ndarray, w_array: PortfolioOptimizationVars
) -> float:
    return sum(returns[i] * w_array.a[i] for i in range(len(returns)))
def risk_cost(covariances: np.ndarray, w_array: PortfolioOptimizationVars) -> float:
    risk_term = sum(
        w_array.a[i]
        * sum(w_array.a[j] * covariances[i][j] for j in range(covariances.shape[0]))
        for i in range(covariances.shape[0])
    )
    return risk_term
def objective_portfolio_inequality(
w_array: PortfolioOptimizationVars,
returns: np.ndarray,
covariances: np.ndarray,
return_coeff: float,
) -> float:
return (
risk_cost(covariances, w_array)
- return_coeff * expected_return_cost(returns, w_array)
+ Penalty
* (
sum(w_array.a[i] for i in range(len(returns)))
+ w_array.slack
- total_budget
)
** 2
)
@qfunc
def mixer_layer(beta: CReal, qba: QArray):
apply_to_all(lambda q: RX(beta, q), qba)
@qfunc
def main(
params: CArray[CReal, 2 * NUM_LAYERS], w_array: Output[PortfolioOptimizationVars]
) -> None:
allocate(w_array)
hadamard_transform(w_array)
repeat(
count=int(params.len / 2),
iteration=lambda i: (
phase(
objective_portfolio_inequality(
w_array, returns, covariances, return_coeff
),
params[2 * i],
),
mixer_layer(params[2 * i + 1], w_array),
),
)
qprog = synthesize(main)
show(qprog)
NUM_SHOTS = 1000
es = ExecutionSession(qprog, num_shots=NUM_SHOTS)
def initial_qaoa_params(NUM_LAYERS) -> np.ndarray:
initial_gammas = math.pi * np.linspace(0, 1, NUM_LAYERS)
initial_betas = math.pi * np.linspace(1, 0, NUM_LAYERS)
initial_params = []
for i in range(NUM_LAYERS):
initial_params.append(initial_gammas[i])
initial_params.append(initial_betas[i])
return np.array(initial_params)
initial_params = initial_qaoa_params(NUM_LAYERS)
# Record the steps of the optimization
intermediate_params = []
objective_values = []


# Define the callback function to store the intermediate steps
def callback(xk):
    intermediate_params.append(xk)
cost_func = lambda state: objective_portfolio_inequality(
w_array=state["w_array"],
returns=returns,
covariances=covariances,
return_coeff=return_coeff,
)
def estimate_cost_func(params: np.ndarray) -> float:
objective_value = es.estimate_cost(
cost_func=cost_func, parameters={"params": params.tolist()}
)
objective_values.append(objective_value)
return objective_value
optimization_res = minimize(
estimate_cost_func,
x0=initial_params,
method="COBYLA",
callback=callback,
options={"maxiter": 20},
)
res = es.sample({"params": optimization_res.x.tolist()})
print(f"Optimized parameters: {optimization_res.x.tolist()}")
sorted_counts = sorted(
res.parsed_counts,
key=lambda pc: objective_portfolio_inequality(
pc.state["w_array"],
returns=returns,
covariances=covariances,
return_coeff=return_coeff,
),
)
for sampled in sorted_counts:
w = sampled.state["w_array"]
print(
f"solution={w} probability={sampled.shots/NUM_SHOTS} "
f"cost={objective_portfolio_inequality(w_array=w,returns = returns, covariances = covariances, return_coeff= return_coeff)}"
)
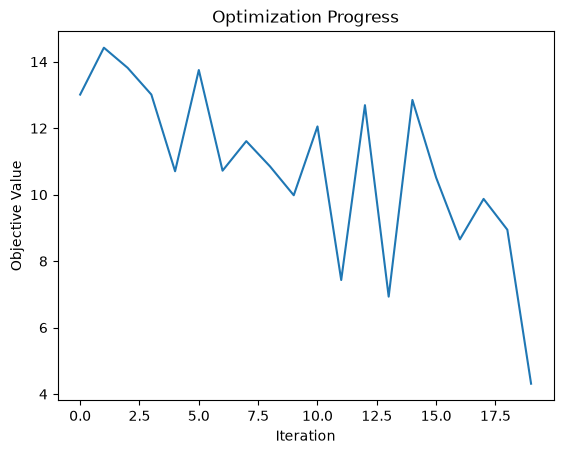
plt.plot(objective_values)
plt.xlabel("Iteration")
plt.ylabel("Objective Value")
plt.title("Optimization Progress")
Output:
Quantum program link: https://platform.classiq.io/circuit/3IoazeHlfc06l4ZBMvzlUE559af
Output:
https://platform.classiq.io/circuit/3IoazeHlfc06l4ZBMvzlUE559af?login=True&version=22
Output:
Optimized parameters: [0.9502643655501141, 4.138281739493553, 1.5713654060432483, 1.5726939726241174, 3.1448084007547488, 0.0010670393627489221]
  solution={'a': [3, 3, 0], 'slack': 0} probability=0.002 cost=-184.8
  solution={'a': [2, 3, 0], 'slack': 1} probability=0.005 cost=-162.3
  solution={'a': [3, 3, 0], 'slack': 1} probability=0.001 cost=-154.3
  solution={'a': [3, 2, 0], 'slack': 1} probability=0.001 cost=-152.3
  solution={'a': [3, 3, 1], 'slack': 0} probability=0.001 cost=-148.8
  solution={'a': [3, 2, 1], 'slack': 0} probability=0.001 cost=-146.4
  solution={'a': [1, 3, 0], 'slack': 2} probability=0.007 cost=-138.0
  solution={'a': [2, 3, 0], 'slack': 2} probability=0.001 cost=-131.8
  solution={'a': [1, 3, 1], 'slack': 1} probability=0.003 cost=-129.7
  solution={'a': [2, 3, 1], 'slack': 1} probability=0.008 cost=-124.9
  solution={'a': [3, 2, 0], 'slack': 2} probability=0.004 cost=-121.80000000000001
  solution={'a': [2, 2, 1], 'slack': 1} probability=0.002 cost=-121.5
  solution={'a': [1, 3, 2], 'slack': 0} probability=0.001 cost=-119.6
  solution={'a': [3, 1, 0], 'slack': 2} probability=0.003 cost=-118.0
  solution={'a': [3, 2, 1], 'slack': 1} probability=0.001 cost=-115.9
  solution={'a': [2, 2, 2], 'slack': 0} probability=0.006 cost=-112.4
  solution={'a': [0, 3, 0], 'slack': 3} probability=0.003 cost=-111.9
  solution={'a': [3, 1, 1], 'slack': 1} probability=0.004 cost=-111.7
  solution={'a': [3, 2, 2], 'slack': 0} probability=0.002 cost=-108.19999999999999
  solution={'a': [1, 3, 0], 'slack': 1} probability=0.004 cost=-107.5
  solution={'a': [3, 1, 2], 'slack': 0} probability=0.002 cost=-103.6
  solution={'a': [1, 2, 0], 'slack': 3} probability=0.003 cost=-103.5
  solution={'a': [0, 3, 1], 'slack': 2} probability=0.001 cost=-102.2
  solution={'a': [1, 3, 1], 'slack': 2} probability=0.002 cost=-99.19999999999999
  solution={'a': [2, 2, 0], 'slack': 1} probability=0.004 cost=-98.30000000000001
  solution={'a': [2, 2, 0], 'slack': 3} probability=0.004 cost=-98.30000000000001
  solution={'a': [1, 2, 1], 'slack': 2} probability=0.004 cost=-94.8
  solution={'a': [2, 1, 0], 'slack': 3} probability=0.002 cost=-93.5
  solution={'a': [2, 2, 1], 'slack': 0} probability=0.005 cost=-91.0
  solution={'a': [0, 3, 2], 'slack': 1} probability=0.001 cost=-90.7
  solution={'a': [1, 3, 2], 'slack': 1} probability=0.004 cost=-89.1
  solution={'a': [2, 1, 1], 'slack': 2} probability=0.003 cost=-85.8
  solution={'a': [1, 2, 2], 'slack': 1} probability=0.003 cost=-84.3
  solution={'a': [2, 2, 2], 'slack': 1} probability=0.004 cost=-81.9
  solution={'a': [0, 3, 0], 'slack': 4} probability=0.003 cost=-81.4
  solution={'a': [0, 3, 3], 'slack': 0} probability=0.014 cost=-77.4
  solution={'a': [1, 3, 3], 'slack': 0} probability=0.002 cost=-77.2
  solution={'a': [2, 1, 2], 'slack': 1} probability=0.014 cost=-76.3
  solution={'a': [3, 0, 1], 'slack': 2} probability=0.002 cost=-75.2
  solution={'a': [3, 1, 2], 'slack': 1} probability=0.001 cost=-73.1
  solution={'a': [1, 2, 0], 'slack': 2} probability=0.004 cost=-73.0
  solution={'a': [0, 3, 1], 'slack': 3} probability=0.001 cost=-71.7
  solution={'a': [0, 3, 1], 'slack': 1} probability=0.001 cost=-71.7
  solution={'a': [2, 2, 3], 'slack': 0} probability=0.002 cost=-71.0
  solution={'a': [1, 1, 0], 'slack': 4} probability=0.001 cost=-67.2
  solution={'a': [3, 0, 2], 'slack': 1} probability=0.002 cost=-66.7
  solution={'a': [0, 2, 1], 'slack': 3} probability=0.002 cost=-66.3
  solution={'a': [1, 2, 1], 'slack': 3} probability=0.002 cost=-64.3
  solution={'a': [3, 1, 3], 'slack': 0} probability=0.003 cost=-63.2
  solution={'a': [2, 1, 0], 'slack': 2} probability=0.006 cost=-63.0
  solution={'a': [2, 1, 0], 'slack': 4} probability=0.002 cost=-63.0
  solution={'a': [3, 3, 0], 'slack': 2} probability=0.001 cost=-62.80000000000001
  solution={'a': [0, 3, 2], 'slack': 0} probability=0.001 cost=-60.2
  solution={'a': [1, 1, 1], 'slack': 3} probability=0.003 cost=-58.1
  solution={'a': [2, 0, 0], 'slack': 4} probability=0.001 cost=-56.4
  solution={'a': [2, 1, 1], 'slack': 1} probability=0.01 cost=-55.3
  solution={'a': [2, 1, 1], 'slack': 3} probability=0.004 cost=-55.3
  solution={'a': [0, 2, 2], 'slack': 2} probability=0.009 cost=-54.4
  solution={'a': [1, 2, 2], 'slack': 0} probability=0.002 cost=-53.8
  solution={'a': [3, 0, 0], 'slack': 2} probability=0.001 cost=-51.400000000000006
  solution={'a': [3, 3, 2], 'slack': 0} probability=0.004 cost=-50.0
  solution={'a': [1, 1, 2], 'slack': 2} probability=0.005 cost=-47.2
  solution={'a': [0, 3, 3], 'slack': 1} probability=0.002 cost=-46.900000000000006
  solution={'a': [0, 2, 0], 'slack': 5} probability=0.008 cost=-45.900000000000006
  solution={'a': [0, 2, 0], 'slack': 3} probability=0.008 cost=-45.900000000000006
  solution={'a': [3, 0, 1], 'slack': 1} probability=0.002 cost=-44.7
  solution={'a': [3, 0, 1], 'slack': 3} probability=0.002 cost=-44.7
  solution={'a': [1, 2, 3], 'slack': 1} probability=0.003 cost=-41.5
  solution={'a': [2, 3, 0], 'slack': 3} probability=0.001 cost=-40.30000000000001
  solution={'a': [0, 1, 0], 'slack': 5} probability=0.001 cost=-39.1
  solution={'a': [2, 0, 2], 'slack': 2} probability=0.006 cost=-38.4
  solution={'a': [1, 1, 0], 'slack': 3} probability=0.004 cost=-36.7
  solution={'a': [1, 1, 0], 'slack': 5} probability=0.001 cost=-36.7
  solution={'a': [3, 0, 2], 'slack': 0} probability=0.002 cost=-36.2
  solution={'a': [3, 0, 2], 'slack': 2} probability=0.002 cost=-36.2
  solution={'a': [0, 2, 1], 'slack': 4} probability=0.004 cost=-35.8
  solution={'a': [2, 1, 3], 'slack': 1} probability=0.002 cost=-34.5
  solution={'a': [1, 1, 3], 'slack': 1} probability=0.002 cost=-34.5
  solution={'a': [1, 1, 1], 'slack': 2} probability=0.004 cost=-27.6
  solution={'a': [1, 1, 1], 'slack': 4} probability=0.001 cost=-27.6
  solution={'a': [2, 0, 0], 'slack': 5} probability=0.002 cost=-25.9
  solution={'a': [2, 0, 0], 'slack': 3} probability=0.002 cost=-25.9
  solution={'a': [3, 0, 3], 'slack': 1} probability=0.001 cost=-25.9
  solution={'a': [2, 3, 2], 'slack': 1} probability=0.001 cost=-24.69999999999999
  solution={'a': [3, 2, 1], 'slack': 2} probability=0.005 cost=-24.400000000000006
  solution={'a': [0, 2, 2], 'slack': 3} probability=0.004 cost=-23.9
  solution={'a': [0, 2, 2], 'slack': 1} probability=0.003 cost=-23.9
  solution={'a': [1, 0, 1], 'slack': 4} probability=0.001 cost=-19.6
  solution={'a': [2, 0, 1], 'slack': 4} probability=0.002 cost=-17.799999999999997
  solution={'a': [1, 1, 2], 'slack': 3} probability=0.003 cost=-16.700000000000003
  solution={'a': [3, 2, 2], 'slack': 1} probability=0.004 cost=-16.69999999999999
  solution={'a': [0, 1, 2], 'slack': 3} probability=0.001 cost=-16.3
  solution={'a': [1, 3, 0], 'slack': 0} probability=0.002 cost=-16.0
  solution={'a': [2, 3, 3], 'slack': 0} probability=0.002 cost=-14.199999999999989
  solution={'a': [0, 2, 3], 'slack': 2} probability=0.003 cost=-10.200000000000003
  solution={'a': [0, 2, 3], 'slack': 0} probability=0.003 cost=-10.200000000000003
  solution={'a': [0, 1, 0], 'slack': 6} probability=0.001 cost=-8.600000000000001
  solution={'a': [2, 0, 2], 'slack': 1} probability=0.003 cost=-7.899999999999999
  solution={'a': [1, 3, 1], 'slack': 3} probability=0.002 cost=-7.699999999999989
  solution={'a': [1, 1, 3], 'slack': 2} probability=0.002 cost=-4.0
  solution={'a': [0, 1, 3], 'slack': 2} probability=0.001 cost=-2.2
  solution={'a': [0, 0, 0], 'slack': 6} probability=0.001 cost=0.0
  solution={'a': [2, 2, 1], 'slack': 3} probability=0.002 cost=0.5
  solution={'a': [1, 0, 0], 'slack': 4} probability=0.003 cost=1.3999999999999986
  solution={'a': [1, 0, 0], 'slack': 6} probability=0.003 cost=1.3999999999999986
  solution={'a': [0, 1, 1], 'slack': 3} probability=0.003 cost=1.8999999999999986
  solution={'a': [1, 3, 2], 'slack': 2} probability=0.002 cost=2.4000000000000057
  solution={'a': [2, 0, 3], 'slack': 2} probability=0.011 cost=3.8000000000000007
  solution={'a': [2, 2, 2], 'slack': 2} probability=0.002 cost=9.599999999999994
  solution={'a': [0, 3, 0], 'slack': 5} probability=0.003 cost=10.099999999999994
  solution={'a': [0, 3, 0], 'slack': 1} probability=0.002 cost=10.099999999999994
  solution={'a': [1, 0, 1], 'slack': 3} probability=0.003 cost=10.899999999999999
  solution={'a': [0, 1, 2], 'slack': 4} probability=0.003 cost=14.2
  solution={'a': [1, 3, 3], 'slack': 1} probability=0.005 cost=14.299999999999997
  solution={'a': [3, 1, 2], 'slack': 2} probability=0.009 cost=18.400000000000006
  solution={'a': [1, 2, 0], 'slack': 1} probability=0.002 cost=18.5
  solution={'a': [1, 2, 0], 'slack': 5} probability=0.002 cost=18.5
  solution={'a': [0, 3, 1], 'slack': 4} probability=0.002 cost=19.799999999999997
  solution={'a': [0, 3, 1], 'slack': 0} probability=0.001 cost=19.799999999999997
  solution={'a': [1, 0, 2], 'slack': 2} probability=0.001 cost=22.2
  solution={'a': [3, 1, 3], 'slack': 1} probability=0.011 cost=28.299999999999997
  solution={'a': [0, 1, 3], 'slack': 1} probability=0.009 cost=28.3
  solution={'a': [0, 1, 3], 'slack': 3} probability=0.004 cost=28.3
  solution={'a': [2, 1, 0], 'slack': 1} probability=0.001 cost=28.5
  solution={'a': [0, 3, 2], 'slack': 3} probability=0.001 cost=31.299999999999997
  solution={'a': [1, 0, 3], 'slack': 1} probability=0.003 cost=35.3
  solution={'a': [2, 1, 1], 'slack': 0} probability=0.005 cost=36.2
  solution={'a': [1, 2, 2], 'slack': 3} probability=0.01 cost=37.7
  solution={'a': [3, 0, 0], 'slack': 5} probability=0.001 cost=40.099999999999994
  solution={'a': [3, 0, 0], 'slack': 1} probability=0.001 cost=40.099999999999994
  solution={'a': [0, 3, 3], 'slack': 2} probability=0.002 cost=44.599999999999994
  solution={'a': [0, 2, 0], 'slack': 2} probability=0.001 cost=45.599999999999994
  solution={'a': [2, 1, 2], 'slack': 3} probability=0.004 cost=45.7
  solution={'a': [3, 0, 1], 'slack': 0} probability=0.001 cost=46.8
  solution={'a': [1, 2, 3], 'slack': 2} probability=0.004 cost=50.0
  solution={'a': [0, 0, 2], 'slack': 3} probability=0.001 cost=54.1
  solution={'a': [1, 1, 0], 'slack': 6} probability=0.001 cost=54.8
  solution={'a': [0, 2, 1], 'slack': 1} probability=0.001 cost=55.7
  solution={'a': [1, 1, 1], 'slack': 1} probability=0.005 cost=63.9
  solution={'a': [1, 1, 1], 'slack': 5} probability=0.001 cost=63.9
  solution={'a': [3, 0, 3], 'slack': 2} probability=0.008 cost=65.6
  solution={'a': [2, 0, 0], 'slack': 6} probability=0.001 cost=65.6
  solution={'a': [0, 2, 2], 'slack': 0} probability=0.009 cost=67.6
  solution={'a': [0, 2, 2], 'slack': 4} probability=0.001 cost=67.6
  solution={'a': [0, 0, 3], 'slack': 4} probability=0.003 cost=68.6
  solution={'a': [0, 0, 3], 'slack': 2} probability=0.001 cost=68.6
  solution={'a': [2, 0, 1], 'slack': 1} probability=0.004 cost=73.7
  solution={'a': [2, 0, 1], 'slack': 5} probability=0.001 cost=73.7
  solution={'a': [1, 1, 2], 'slack': 0} probability=0.004 cost=74.8
  solution={'a': [0, 1, 0], 'slack': 7} probability=0.003 cost=82.9
  solution={'a': [2, 0, 2], 'slack': 0} probability=0.001 cost=83.6
  solution={'a': [1, 1, 3], 'slack': 3} probability=0.007 cost=87.5
  solution={'a': [3, 3, 0], 'slack': 3} probability=0.001 cost=89.69999999999999
  solution={'a': [1, 0, 0], 'slack': 3} probability=0.003 cost=92.9
  solution={'a': [1, 0, 0], 'slack': 7} probability=0.001 cost=92.9
  solution={'a': [0, 1, 1], 'slack': 2} probability=0.002 cost=93.4
  solution={'a': [0, 1, 1], 'slack': 6} probability=0.001 cost=93.4
  solution={'a': [2, 0, 3], 'slack': 3} probability=0.003 cost=95.3
  solution={'a': [1, 0, 1], 'slack': 2} probability=0.003 cost=102.4
  solution={'a': [1, 0, 1], 'slack': 6} probability=0.002 cost=102.4
  solution={'a': [0, 1, 2], 'slack': 1} probability=0.006 cost=105.7
  solution={'a': [0, 1, 2], 'slack': 5} probability=0.001 cost=105.7
  solution={'a': [3, 3, 3], 'slack': 0} probability=0.001 cost=111.6
  solution={'a': [1, 0, 2], 'slack': 1} probability=0.004 cost=113.7
  solution={'a': [2, 3, 1], 'slack': 3} probability=0.005 cost=119.1
  solution={'a': [0, 1, 3], 'slack': 0} probability=0.001 cost=119.8
  solution={'a': [1, 0, 3], 'slack': 0} probability=0.003 cost=126.8
  solution={'a': [1, 0, 3], 'slack': 4} probability=0.002 cost=126.8
  solution={'a': [3, 2, 1], 'slack': 3} probability=0.002 cost=128.1
  solution={'a': [0, 0, 1], 'slack': 3} probability=0.002 cost=132.9
  solution={'a': [3, 2, 2], 'slack': 2} probability=0.001 cost=135.8
  solution={'a': [2, 3, 3], 'slack': 1} probability=0.003 cost=138.3
  solution={'a': [1, 3, 1], 'slack': 4} probability=0.001 cost=144.8
  solution={'a': [3, 2, 3], 'slack': 1} probability=0.004 cost=145.3
  solution={'a': [0, 0, 2], 'slack': 2} probability=0.005 cost=145.6
  solution={'a': [0, 0, 2], 'slack': 6} probability=0.002 cost=145.6
  solution={'a': [2, 2, 0], 'slack': 5} probability=0.006 cost=145.7
  solution={'a': [2, 2, 1], 'slack': 4} probability=0.001 cost=153.0
  solution={'a': [0, 0, 3], 'slack': 1} probability=0.002 cost=160.1
  solution={'a': [2, 2, 2], 'slack': 3} probability=0.008 cost=162.1
  solution={'a': [0, 3, 0], 'slack': 6} probability=0.001 cost=162.6
  solution={'a': [3, 1, 1], 'slack': 4} probability=0.007 cost=162.8
  solution={'a': [1, 3, 3], 'slack': 2} probability=0.001 cost=166.8
  solution={'a': [3, 1, 2], 'slack': 3} probability=0.007 cost=170.9
  solution={'a': [1, 2, 0], 'slack': 0} probability=0.005 cost=171.0
  solution={'a': [1, 2, 0], 'slack': 6} probability=0.003 cost=171.0
  solution={'a': [1, 2, 1], 'slack': 5} probability=0.001 cost=179.7
  solution={'a': [3, 1, 3], 'slack': 2} probability=0.002 cost=180.8
  solution={'a': [2, 1, 0], 'slack': 0} probability=0.002 cost=181.0
  solution={'a': [2, 1, 0], 'slack': 6} probability=0.001 cost=181.0
  solution={'a': [0, 3, 2], 'slack': 4} probability=0.002 cost=183.8
  solution={'a': [2, 1, 1], 'slack': 5} probability=0.001 cost=188.7
  solution={'a': [1, 2, 2], 'slack': 4} probability=0.001 cost=190.2
  solution={'a': [3, 0, 0], 'slack': 0} probability=0.005 cost=192.6
  solution={'a': [0, 3, 3], 'slack': 3} probability=0.003 cost=197.1
  solution={'a': [0, 2, 0], 'slack': 1} probability=0.008 cost=198.1
  solution={'a': [1, 2, 3], 'slack': 3} probability=0.004 cost=202.5
  solution={'a': [1, 1, 0], 'slack': 1} probability=0.009 cost=207.3
  solution={'a': [3, 0, 2], 'slack': 4} probability=0.001 cost=207.8
  solution={'a': [0, 2, 1], 'slack': 0} probability=0.001 cost=208.2
  solution={'a': [2, 1, 3], 'slack': 3} probability=0.002 cost=209.5
  solution={'a': [1, 1, 1], 'slack': 6} probability=0.002 cost=216.4
  solution={'a': [1, 1, 1], 'slack': 0} probability=0.001 cost=216.4
  solution={'a': [2, 0, 0], 'slack': 1} probability=0.01 cost=218.1
  solution={'a': [2, 0, 0], 'slack': 7} probability=0.002 cost=218.1
  solution={'a': [3, 0, 3], 'slack': 3} probability=0.001 cost=218.1
  solution={'a': [0, 2, 2], 'slack': 5} probability=0.004 cost=220.1
  solution={'a': [2, 0, 1], 'slack': 0} probability=0.009 cost=226.2
  solution={'a': [1, 1, 2], 'slack': 5} probability=0.001 cost=227.3
  solution={'a': [0, 1, 0], 'slack': 2} probability=0.002 cost=235.4
  solution={'a': [1, 0, 0], 'slack': 2} probability=0.021 cost=245.4
  solution={'a': [0, 1, 1], 'slack': 7} probability=0.005 cost=245.9
  solution={'a': [0, 1, 1], 'slack': 1} probability=0.004 cost=245.9
  solution={'a': [1, 0, 1], 'slack': 1} probability=0.006 cost=254.9
  solution={'a': [0, 1, 2], 'slack': 0} probability=0.001 cost=258.2
  solution={'a': [0, 1, 2], 'slack': 6} probability=0.001 cost=258.2
  solution={'a': [1, 0, 2], 'slack': 0} probability=0.005 cost=266.2
  solution={'a': [1, 0, 2], 'slack': 6} probability=0.002 cost=266.2
  solution={'a': [0, 1, 3], 'slack': 5} probability=0.005 cost=272.3
  solution={'a': [0, 0, 0], 'slack': 3} probability=0.002 cost=274.5
  solution={'a': [1, 0, 3], 'slack': 5} probability=0.006 cost=279.3
  solution={'a': [0, 0, 2], 'slack': 1} probability=0.001 cost=298.1
  solution={'a': [3, 3, 0], 'slack': 4} probability=0.001 cost=303.2
  solution={'a': [0, 0, 3], 'slack': 0} probability=0.005 cost=312.6
  solution={'a': [0, 0, 3], 'slack': 6} probability=0.001 cost=312.6
  solution={'a': [3, 3, 2], 'slack': 2} probability=0.002 cost=316.0
  solution={'a': [3, 3, 3], 'slack': 1} probability=0.001 cost=325.1
  solution={'a': [2, 3, 0], 'slack': 5} probability=0.004 cost=325.7
  solution={'a': [2, 3, 1], 'slack': 4} probability=0.002 cost=332.6
  solution={'a': [3, 2, 0], 'slack': 5} probability=0.005 cost=335.7
  solution={'a': [2, 3, 2], 'slack': 3} probability=0.004 cost=341.3
  solution={'a': [3, 2, 2], 'slack': 3} probability=0.003 cost=349.3
  solution={'a': [2, 3, 3], 'slack': 2} probability=0.001 cost=351.8
  solution={'a': [1, 3, 1], 'slack': 5} probability=0.001 cost=358.3
  solution={'a': [3, 2, 3], 'slack': 2} probability=0.003 cost=358.8
  solution={'a': [2, 2, 1], 'slack': 5} probability=0.004 cost=366.5
  solution={'a': [1, 3, 2], 'slack': 4} probability=0.001 cost=368.4
  solution={'a': [3, 1, 1], 'slack': 5} probability=0.012 cost=376.3
  solution={'a': [1, 3, 3], 'slack': 3} probability=0.001 cost=380.3
  solution={'a': [3, 1, 2], 'slack': 4} probability=0.003 cost=384.4
  solution={'a': [1, 2, 0], 'slack': 7} probability=0.001 cost=384.5
  solution={'a': [3, 1, 3], 'slack': 3} probability=0.003 cost=394.3
  solution={'a': [2, 1, 0], 'slack': 7} probability=0.001 cost=394.5
  solution={'a': [0, 3, 2], 'slack': 5} probability=0.003 cost=397.3
  solution={'a': [1, 2, 2], 'slack': 5} probability=0.005 cost=403.7
  solution={'a': [3, 0, 0], 'slack': 7} probability=0.001 cost=406.1
  solution={'a': [0, 3, 3], 'slack': 4} probability=0.001 cost=410.6
  solution={'a': [2, 1, 2], 'slack': 5} probability=0.009 cost=411.7
  solution={'a': [3, 0, 1], 'slack': 6} probability=0.002 cost=412.8
  solution={'a': [1, 1, 0], 'slack': 0} probability=0.005 cost=420.8
  solution={'a': [3, 0, 2], 'slack': 5} probability=0.003 cost=421.3
  solution={'a': [0, 2, 1], 'slack': 7} probability=0.002 cost=421.7
  solution={'a': [2, 1, 3], 'slack': 4} probability=0.003 cost=423.0
  solution={'a': [2, 0, 0], 'slack': 0} probability=0.004 cost=431.6
  solution={'a': [0, 2, 2], 'slack': 6} probability=0.001 cost=433.6
  solution={'a': [2, 0, 1], 'slack': 7} probability=0.001 cost=439.7
  solution={'a': [1, 1, 2], 'slack': 6} probability=0.001 cost=440.8
  solution={'a': [0, 1, 0], 'slack': 1} probability=0.001 cost=448.9
  solution={'a': [2, 0, 2], 'slack': 6} probability=0.005 cost=449.6
  solution={'a': [1, 0, 0], 'slack': 1} probability=0.008 cost=458.9
  solution={'a': [1, 0, 1], 'slack': 0} probability=0.001 cost=468.4
  solution={'a': [1, 0, 2], 'slack': 7} probability=0.001 cost=479.7
  solution={'a': [0, 0, 0], 'slack': 2} probability=0.004 cost=488.0
  solution={'a': [0, 0, 2], 'slack': 0} probability=0.002 cost=511.6
  solution={'a': [3, 3, 2], 'slack': 3} probability=0.002 cost=590.5
  solution={'a': [3, 3, 3], 'slack': 2} probability=0.012 cost=599.6
  solution={'a': [2, 3, 0], 'slack': 6} probability=0.001 cost=600.2
  solution={'a': [2, 3, 1], 'slack': 5} probability=0.003 cost=607.1
  solution={'a': [3, 2, 0], 'slack': 6} probability=0.001 cost=610.2
  solution={'a': [2, 3, 2], 'slack': 4} probability=0.002 cost=615.8
  solution={'a': [3, 2, 1], 'slack': 5} probability=0.001 cost=616.1
  solution={'a': [3, 2, 3], 'slack': 3} probability=0.002 cost=633.3
  solution={'a': [1, 3, 2], 'slack': 5} probability=0.004 cost=642.9
  solution={'a': [3, 1, 0], 'slack': 7} probability=0.002 cost=644.5
  solution={'a': [2, 2, 2], 'slack': 5} probability=0.002 cost=650.1
  solution={'a': [3, 1, 1], 'slack': 6} probability=0.002 cost=650.8
  solution={'a': [1, 3, 3], 'slack': 4} probability=0.001 cost=654.8
  solution={'a': [0, 3, 1], 'slack': 7} probability=0.002 cost=660.3
  solution={'a': [3, 1, 3], 'slack': 4} probability=0.003 cost=668.8
  solution={'a': [0, 3, 3], 'slack': 5} probability=0.002 cost=685.1
  solution={'a': [2, 1, 2], 'slack': 6} probability=0.002 cost=686.2
  solution={'a': [3, 0, 2], 'slack': 6} probability=0.003 cost=695.8
  solution={'a': [3, 0, 3], 'slack': 5} probability=0.002 cost=706.1
  solution={'a': [1, 1, 2], 'slack': 7} probability=0.003 cost=715.3
  solution={'a': [0, 2, 3], 'slack': 6} probability=0.003 cost=721.8
  solution={'a': [2, 0, 2], 'slack': 7} probability=0.002 cost=724.1
  solution={'a': [1, 1, 3], 'slack': 6} probability=0.001 cost=728.0
  solution={'a': [1, 0, 0], 'slack': 0} probability=0.001 cost=733.4
  solution={'a': [2, 0, 3], 'slack': 6} probability=0.003 cost=735.8
  solution={'a': [0, 0, 0], 'slack': 1} probability=0.002 cost=762.5
  solution={'a': [0, 0, 1], 'slack': 0} probability=0.007 cost=773.4
  solution={'a': [3, 3, 0], 'slack': 6} probability=0.001 cost=913.2
  solution={'a': [3, 3, 1], 'slack': 5} probability=0.002 cost=918.7
  solution={'a': [2, 3, 1], 'slack': 6} probability=0.003 cost=942.6
  solution={'a': [3, 2, 0], 'slack': 7} probability=0.007 cost=945.7
  solution={'a': [2, 3, 2], 'slack': 5} probability=0.001 cost=951.3
  solution={'a': [3, 2, 1], 'slack': 6} probability=0.001 cost=951.6
  solution={'a': [2, 3, 3], 'slack': 4} probability=0.002 cost=961.8
  solution={'a': [3, 2, 3], 'slack': 4} probability=0.001 cost=968.8
  solution={'a': [2, 2, 1], 'slack': 7} probability=0.002 cost=976.5
  solution={'a': [1, 3, 2], 'slack': 6} probability=0.001 cost=978.4
  solution={'a': [3, 1, 2], 'slack': 6} probability=0.002 cost=994.4
  solution={'a': [2, 2, 3], 'slack': 5} probability=0.001 cost=996.5
  solution={'a': [0, 3, 2], 'slack': 7} probability=0.007 cost=1007.3
  solution={'a': [1, 2, 2], 'slack': 7} probability=0.003 cost=1013.7
  solution={'a': [2, 1, 3], 'slack': 6} probability=0.001 cost=1033.0
  solution={'a': [0, 2, 3], 'slack': 7} probability=0.001 cost=1057.3
  solution={'a': [2, 0, 3], 'slack': 7} probability=0.002 cost=1071.3
  solution={'a': [3, 3, 0], 'slack': 7} probability=0.002 cost=1309.7
  solution={'a': [3, 3, 2], 'slack': 5} probability=0.001 cost=1322.5
  solution={'a': [2, 3, 2], 'slack': 6} probability=0.005 cost=1347.8
  solution={'a': [3, 2, 1], 'slack': 7} probability=0.007 cost=1348.1
  solution={'a': [3, 2, 3], 'slack': 5} probability=0.002 cost=1365.3
  solution={'a': [1, 3, 2], 'slack': 7} probability=0.003 cost=1374.9
  solution={'a': [2, 2, 2], 'slack': 7} probability=0.001 cost=1382.1
  solution={'a': [1, 3, 3], 'slack': 6} probability=0.002 cost=1386.8
  solution={'a': [3, 1, 3], 'slack': 6} probability=0.002 cost=1400.8
  solution={'a': [1, 2, 3], 'slack': 7} probability=0.003 cost=1422.5
  solution={'a': [3, 0, 3], 'slack': 7} probability=0.002 cost=1438.1
  solution={'a': [3, 3, 1], 'slack': 7} probability=0.002 cost=1772.7
  solution={'a': [3, 3, 2], 'slack': 6} probability=0.008 cost=1780.0
  solution={'a': [2, 3, 2], 'slack': 7} probability=0.001 cost=1805.3
  solution={'a': [2, 3, 3], 'slack': 6} probability=0.004 cost=1815.8
  solution={'a': [3, 2, 3], 'slack': 6} probability=0.001 cost=1822.8
  solution={'a': [1, 3, 3], 'slack': 7} probability=0.002 cost=1844.3
  solution={'a': [3, 3, 2], 'slack': 7} probability=0.004 cost=2298.5
  solution={'a': [2, 3, 3], 'slack': 7} probability=0.002 cost=2334.3
  solution={'a': [3, 2, 3], 'slack': 7} probability=0.001 cost=2341.3
  solution={'a': [3, 3, 3], 'slack': 7} probability=0.002 cost=2887.1
Output:
Text(0.5, 1.0, 'Optimization Progress')